The Complete Picture of Every U.S. Retirement Plan
RetireFax is a searchable database of every private-sector retirement plan's Form 5500 since 2015. Each plan shows its recordkeeper and what it's paid, its fund lineup, its history, and how it rates against similar plans.
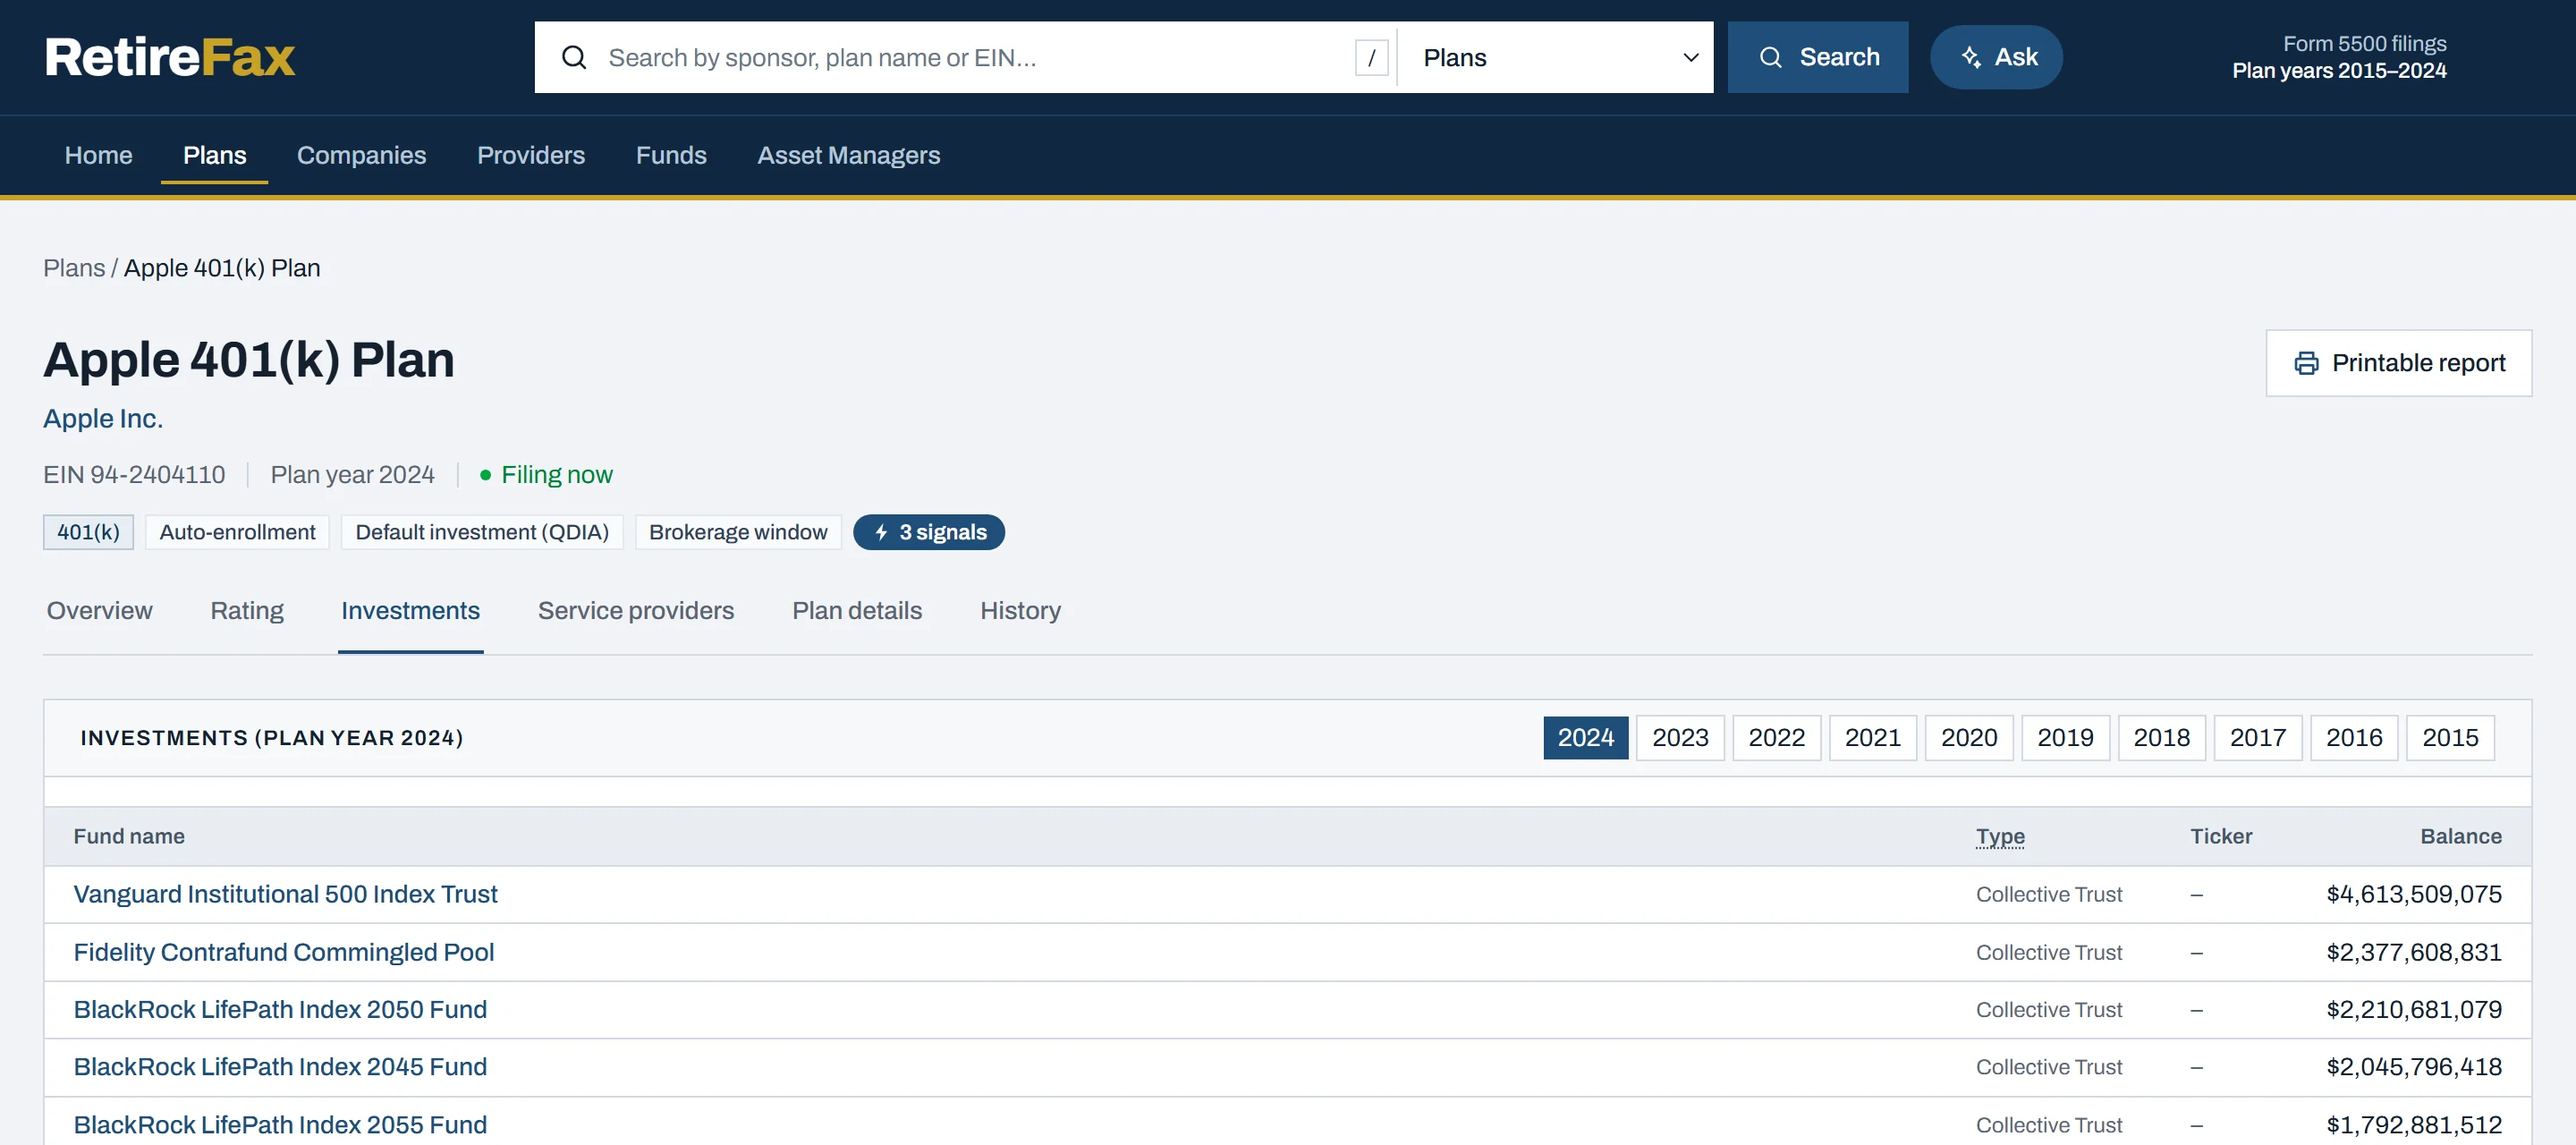
The Apple 401(k) Plan in RetireFax: its 2024 lineup, read from the plan's audited financial statements.
1.3M
Retirement Plans
Every private-sector plan that filed a Form 5500 from 2015 to 2024
1.19M
Plan Sponsors
Each employer with all of its plans in one place
10 Years
of Filings
Plan years 2015 through 2024, followed across renames and number changes
60,000+
Fund Lineups
2024 lineups read from plans' audited financial statements
Ratings for 400,000 Plans
Every defined contribution plan gets a score out of 100 from its last three years of filings, and a rank against plans of the same type, size and industry.
- The Score
- Savings, employer contributions, cost, governance, plan design and outcomes, weighted.
- Switch Likelihood
- Each plan's chance of changing recordkeeper next year, and the reasons.
- Signals
- Facts worth a call, such as retail share classes or no automatic enrollment.
Example 401(k) Plan
401(k) · 1,000–5,000 participants · Manufacturing
78/100
Who Uses RetireFax
Asset Managers and DCIO Teams
Every plan holding your funds and your competitors', with the dollars in each, the vehicle, and who recordkeeps and advises the plan.
1,104 plans list Vanguard Target Retirement 2050 Trust in their audited lineup.
Recordkeepers and Service Providers
Market share by segment, every plan won and lost, each plan's chance of switching next year, and what providers are paid.
2,390 401(k)-type plans changed recordkeepers in 2024.
Advisors and Consultants
Plans in your territory by size, industry and provider, with each plan's rating and ten years of history before the first call.
598 Massachusetts 401(k)s with 100 to 500 participants list no advisor.
How the Data Is Built
We start with every Form 5500 and 5500-SF filed since 2015, their schedules, and the audited financial statements attached to them.
Then we clean it. Each firm's dozens of spellings become one name. A plan keeps its history when it changes its name or number. A firm being bought isn't counted as plans switching. Fund lineups are read line by line and totaled against the form.
Anything unclear is flagged rather than guessed, and a blank means not reported, never zero.
How We Check It
- Within 1%
- of the Department of Labor's own 2022 totals ($10.89 trillion vs. $11.00 trillion).
- 2,213
- plan-years spot-checked against the Department of Labor's filing search; every one found matched.
- 200+
- automated checks on every build. If one fails, nothing is published.
Questions
Anything else: hello@retirefax.com
Where does the data come from?
From public filings: the Form 5500 reports retirement plans file with the U.S. Department of Labor each year, their schedules, and the audited financial statements attached to them. Fund details are matched to the SEC's public fund lists.
Which plans are covered?
Every private-sector plan that filed a Form 5500 or 5500-SF for plan years 2015 through 2024: 401(k), 403(b), profit-sharing, pension, cash balance and ESOP plans. Government plans and most church plans don't file, so they aren't included.
Why do only some plans show providers and fund lineups?
Large plans, generally those with 100 or more participants with account balances, must list their service providers on Schedule C, file full financial statements and attach an independent audit. Smaller plans file a short form without those details.
How current is it?
Plans file up to seven months after their plan year ends, or later with an extension, so a calendar-year plan's 2024 filing can arrive as late as October 2025. We add filings as the Department of Labor publishes them.
How is this different from searching the Department of Labor's site?
The government's search shows one filing at a time, exactly as filed. RetireFax connects a plan's years, merges each firm's many spellings, reads fund lineups out of the audited statements, and lets you search and compare across every plan at once.
How are plans rated?
Each defined contribution plan gets points out of 100 from six parts: savings, employer contributions, cost, governance, plan design and outcomes, measured over its last three years of filings. It's then ranked against plans of the same type, size and industry. Small plans that file the short form are scored without the cost part, since the form rarely reports fees, and are compared only with each other. Missing data is left out, never counted against a plan.
Is this investment advice?
No. RetireFax provides information from public filings. It isn't a recommendation about any investment, provider or plan.
See RetireFax on Your Own Market
A 30-minute walkthrough on the plans, providers and funds you sell to.